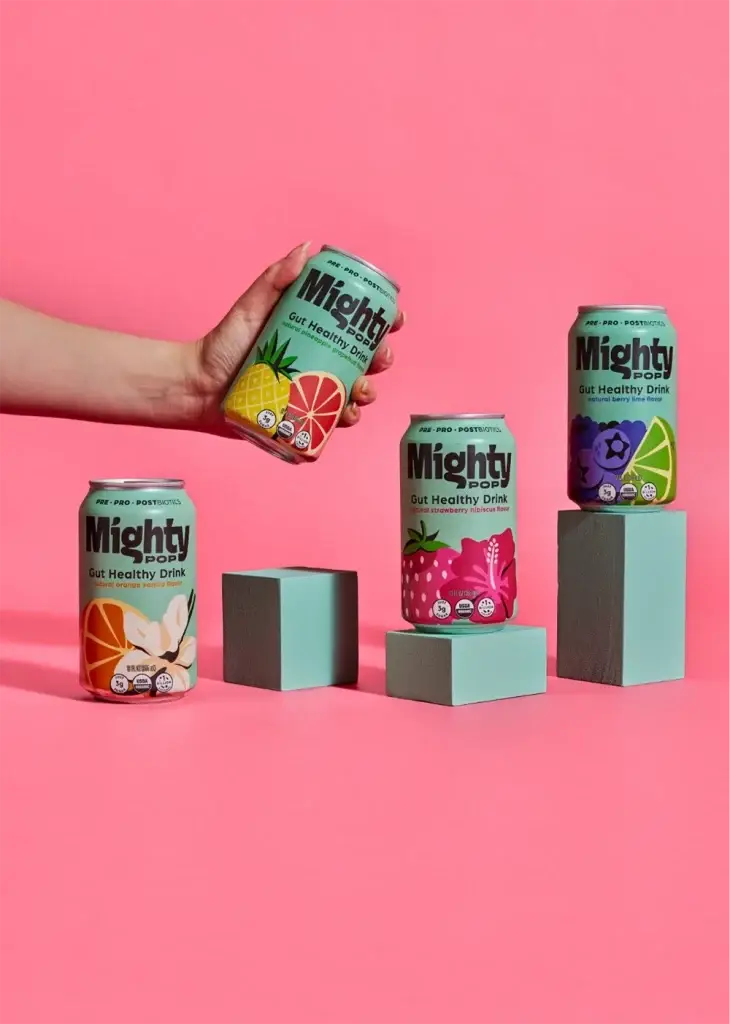

The fastest-growing segments in beverage right now are non-alcoholic RTD and THC-infused drinks. They share almost nothing in terms of ingredients, regulatory status, or distribution pathway. But they share one positioning strategy that is driving their growth: neither of them leads with what is in the can.
They lead with what the product does for the person drinking it.
That is not a minor messaging distinction. It represents a fundamental shift in how beverage brands are building market position in 2026. And the brands that have not made that shift yet are competing in a category that is leaving them behind.
The Non-Alc Category Is Not Playing Defense
Non-alcoholic RTD is not a niche market for people who cannot drink. It is a mainstream category with serious distribution ambitions. Hiyo, backed by Constellation Brands, just expanded to nearly 2,000 Target stores.
Alcoholic RTD cocktails are running roughly 40% ahead year-to-date, representing approximately one quarter of total RTD dollars. Non-alc craft formats are entering the market with flavor-forward positioning and zero ABV as a feature, not a compromise.
The brands leading this expansion are not marketing zero-ABV as an absence. They are not saying “all the fun, none of the alcohol.” They are building specific lifestyle and functional identities that make the product appealing on its own terms. Better sleep. Lower anxiety. Social ease without the next-day cost. These are not compromise claims. They are affirmative reasons to choose the product.
That positioning strategy is winning real shelf space and real distribution because it is recruiting a new consumer, not just serving the sober-curious one.
The THC Beverage Category Is Borrowing a Different Playbook Entirely
THC beverages are moving toward mainstream retail in states where regulatory environments allow it, and the brands gaining traction are not leading with cannabis. They are leading with wellness.
According to MG Magazine’s 2026 cannabis marketing report, 64% of cannabis consumers cite relaxation rather than intoxication as their primary motivation. The brands translating that insight into positioning are outperforming those that lead with potency or percentage. Sleep support. Anxiety reduction. Focus. Social relaxation. These are outcomes-led positioning frameworks borrowed directly from the wellness CPG playbook.
The category is not trying to win by being a better cannabis product. It is trying to win by being a credible wellness product that happens to use THC as the active ingredient. That is a brand strategy decision, not a product decision. And it is creating a very different competitive environment than the one dispensary brands were built for.
Why Ingredient-Led Positioning Stopped Working
Ingredient-led positioning made sense when ingredients were proprietary or when consumers were learning a category for the first time. Both conditions have eroded across beverage.
Consumers are more sophisticated about formulation than they were five years ago. They have read enough labels, seen enough marketing, and tried enough products to be skeptical of ingredient claims that are not backed by a brand they trust. An adaptogen claim from a brand they have never heard of means very little. The same claim from a brand they have bought before and felt a benefit from means something.
The brands accumulating that trust are doing it through consistent, outcome-focused brand storytelling. Not through better labels or higher claimed dosages. They are building a brand identity that makes the functional claim credible because the brand itself stands for something specific.
What Beverage Brand Strategy Looks Like When Outcomes Lead
The outcomes-led positioning model winning in both non-alc and THC beverages is not complicated to understand, but it requires real brand strategy work to execute correctly.
The starting point is a genuine consumer insight about what the person is trying to feel or experience, not what they are trying to consume. The product is the mechanism. The outcome is the reason.
From that insight, a brand position is built around a specific territory. Not “refreshing” or “functional” because those are category table stakes. Something more specific: the brand that helps you wind down without the next morning cost. The brand that makes social situations easier for people who are increasingly thoughtful about what they put in their bodies. The brand that gives the ritual without the risk.
That position then anchors everything: visual identity, packaging architecture, naming, channel strategy, and campaign platform. The brands getting this right are not just talking about outcomes in their advertising. They are building their entire brand system around the outcome identity. The product is the proof. The brand is the promise.
Distribution Strategy Is a Brand Strategy Decision
For both non-alc and THC beverage brands, distribution channel is increasingly inseparable from brand positioning. Where your product lives signals what it is.
A non-alc RTD in a specialty wellness retailer carries different brand associations than the same product in a c-store cooler. A THC beverage in a mainstream grocery channel communicates something very different than the same product in a dispensary. These are not logistics decisions. They are positioning decisions with real brand consequences.
The brands building distribution strategies with intention are asking: what does this channel tell our target consumer about who we are and what we are for? The answer shapes the packaging, the price point, the product format, and the marketing support required to win in that environment.
Agency Squid has worked with beverage brands from launch through national distribution, building brand strategy, brand identity, and integrated campaigns for brands competing in exactly this environment. If you are building or repositioning a beverage brand, we should talk.